While the escalating crisis in the Middle East has once again thrust Pakistan into the international spotlight underscoring its critical geopolitical location and strategic diplomatic weight, the state’s external importance stands in sharp contrast to its internal economic vulnerabilities.
Pakistan’s macroeconomic framework remains severely constrained by deep-rooted structural imbalances. Although stringent International Monetary Fund (IMF) stabilization programs and subsequent sovereign credit rating upgrades from agencies like S&P Global and Fitch have staved off immediate default, these interventions offer only temporary liquidity. Deep systemic fractures continue to stifle long-term growth, leaving Pakistan’s economy highly exposed to an increasingly volatile global environment.
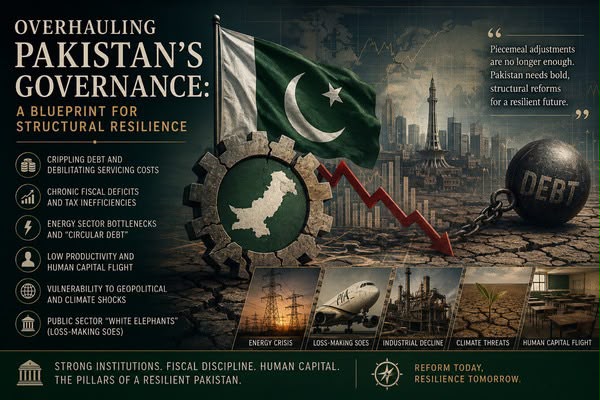
The core structural challenges undermining Pakistan’s economic sustainability can be categorised into the following six major dimensions:
1. Crippling Debt and Debilitating Servicing Costs
Pakistan remains trapped within a severe cycle of compounding domestic and external debt obligations. Debt servicing consumes an unsustainable 60% to 70% of net federal revenue, severely cannibalizing the fiscal space needed for developmental expenditure.
Exorbitant interest payments actively block critical public investments in human capital, healthcare, technical education and infrastructure. The state relies heavily on rolling over multi-billion-dollar bilateral deposits from partners like China, Saudi Arabia, and other Middle Eastern nations simply to maintain a baseline of foreign exchange reserves.
2. Chronic Fiscal Deficits and Tax Inefficiencies
Government revenues historically fail to match expenditures due to widespread tax avoidance, lack of documentation, and structural exemptions granted to powerful lobbies. Recent aggressive policies successfully squeezed an additional 3.2 percentage points of GDP into tax revenue, but maintaining this momentum remains a fiscal tightrope walk.
The domestic banking system is disproportionately exposed to the public sector, with over half of all scheduled bank credit funnelled into financing government debt.
3. Energy Sector Bottlenecks and “Circular Debt”
The energy sector remains a major fiscal black hole, driven by the accumulating financial shortfall known as “circular debt.” A heavy reliance on imported thermal fuel exposes the power grid to sudden global commodity price shocks and drains foreign reserves. Periodic power tariff hikes, implemented to meet strict international lender conditions, inflate the cost of doing business and render local manufacturing globally uncompetitive.
4. Low Productivity and Human Capital Flight
Agriculture employs nearly half the national workforce but suffers from stagnant crop yields, primitive irrigation practices, a lack of modern research, and acute climate vulnerability. Decades of chronically low public expenditure on education have resulted in a poorly skilled, rapidly growing youth population unable to meet modern global market demands.
Prolonged economic stagnation and hyperinflation have triggered a severe “brain drain,” driving the country’s top professional, technical, and digital talent to seek opportunities abroad.
5. Vulnerability to Geopolitical and Climate Shocks
Heightened regional frictions, particularly conflicts affecting Middle Eastern oil supply lines and maritime corridors, rapidly translate into domestic cost-push inflation. Foreign currency reserves remain in a fragile state of recovery from historic lows, leaving negligible breathing room to absorb unexpected external or domestic climate crises.
6. Public Sector “White Elephants” (Loss-Making SOEs)
Massive, mismanaged State-Owned Enterprises (SOEs) drain trillions of rupees from the national exchequer while delivering minimal public utility. Aggregate SOE losses have escalated severely, crossing Rs 832 billion annually, forcing aggressive privatization drives under international lender pressure.
Public utilities such as HESCO (Hyderabad), SEPCO (Sukkur), and QESCO (Quetta) are the largest drivers of domestic economic bleeding among the Power Distribution Companies (DISCOs). Driven by systemic power theft, dilapidated infrastructure, and poor billing collection, they feed a massive circular debt mountain exceeding Rs 5.2 trillion.
Pakistan International Airlines (PIA), the national carrier, is crippled by hundreds of billions of rupees in accumulated losses and toxic liabilities. Marred by deep operational inefficiencies and safety scandals, PIA survives entirely on recurring, taxpayer-funded bailouts.
Pakistan Steel Mills (PSM), located in Karachi, has been completely non-functional for years, paid to stand idle. The state spends billions annually paying salaries to an idle workforce and maintaining dormant machinery, serving as a literal textbook case of institutional waste.
Pakistan Railways is plagued by archaic track systems, outdated locomotives, a bloated pension framework, and frequent safety incidents. Consistently unable to compete with private road transport, it requires massive annual federal subsidies just to sustain basic operations.
The Utility Stores Corporation (USC), a network of state-run grocery outlets, has become structurally broken, inefficient, and vulnerable to corruption. Heavy operational losses have pushed the government to target the USC for complete restructuring or closure to plug fiscal leakages.
Conclusion
It is imperative that Pakistan’s decision-makers immediately overhaul the state’s governance framework to confront these compounding structural crises on an emergency footing. Piecemeal adjustments, ad-hoc tax measures, and short-term stabilization programs are no longer viable.
Without sweeping, aggressive institutional reforms across the economic and administrative landscape, Pakistan cannot unlock its economic potential, attract non-debt foreign investment, or deliver sustainable macroeconomic results.